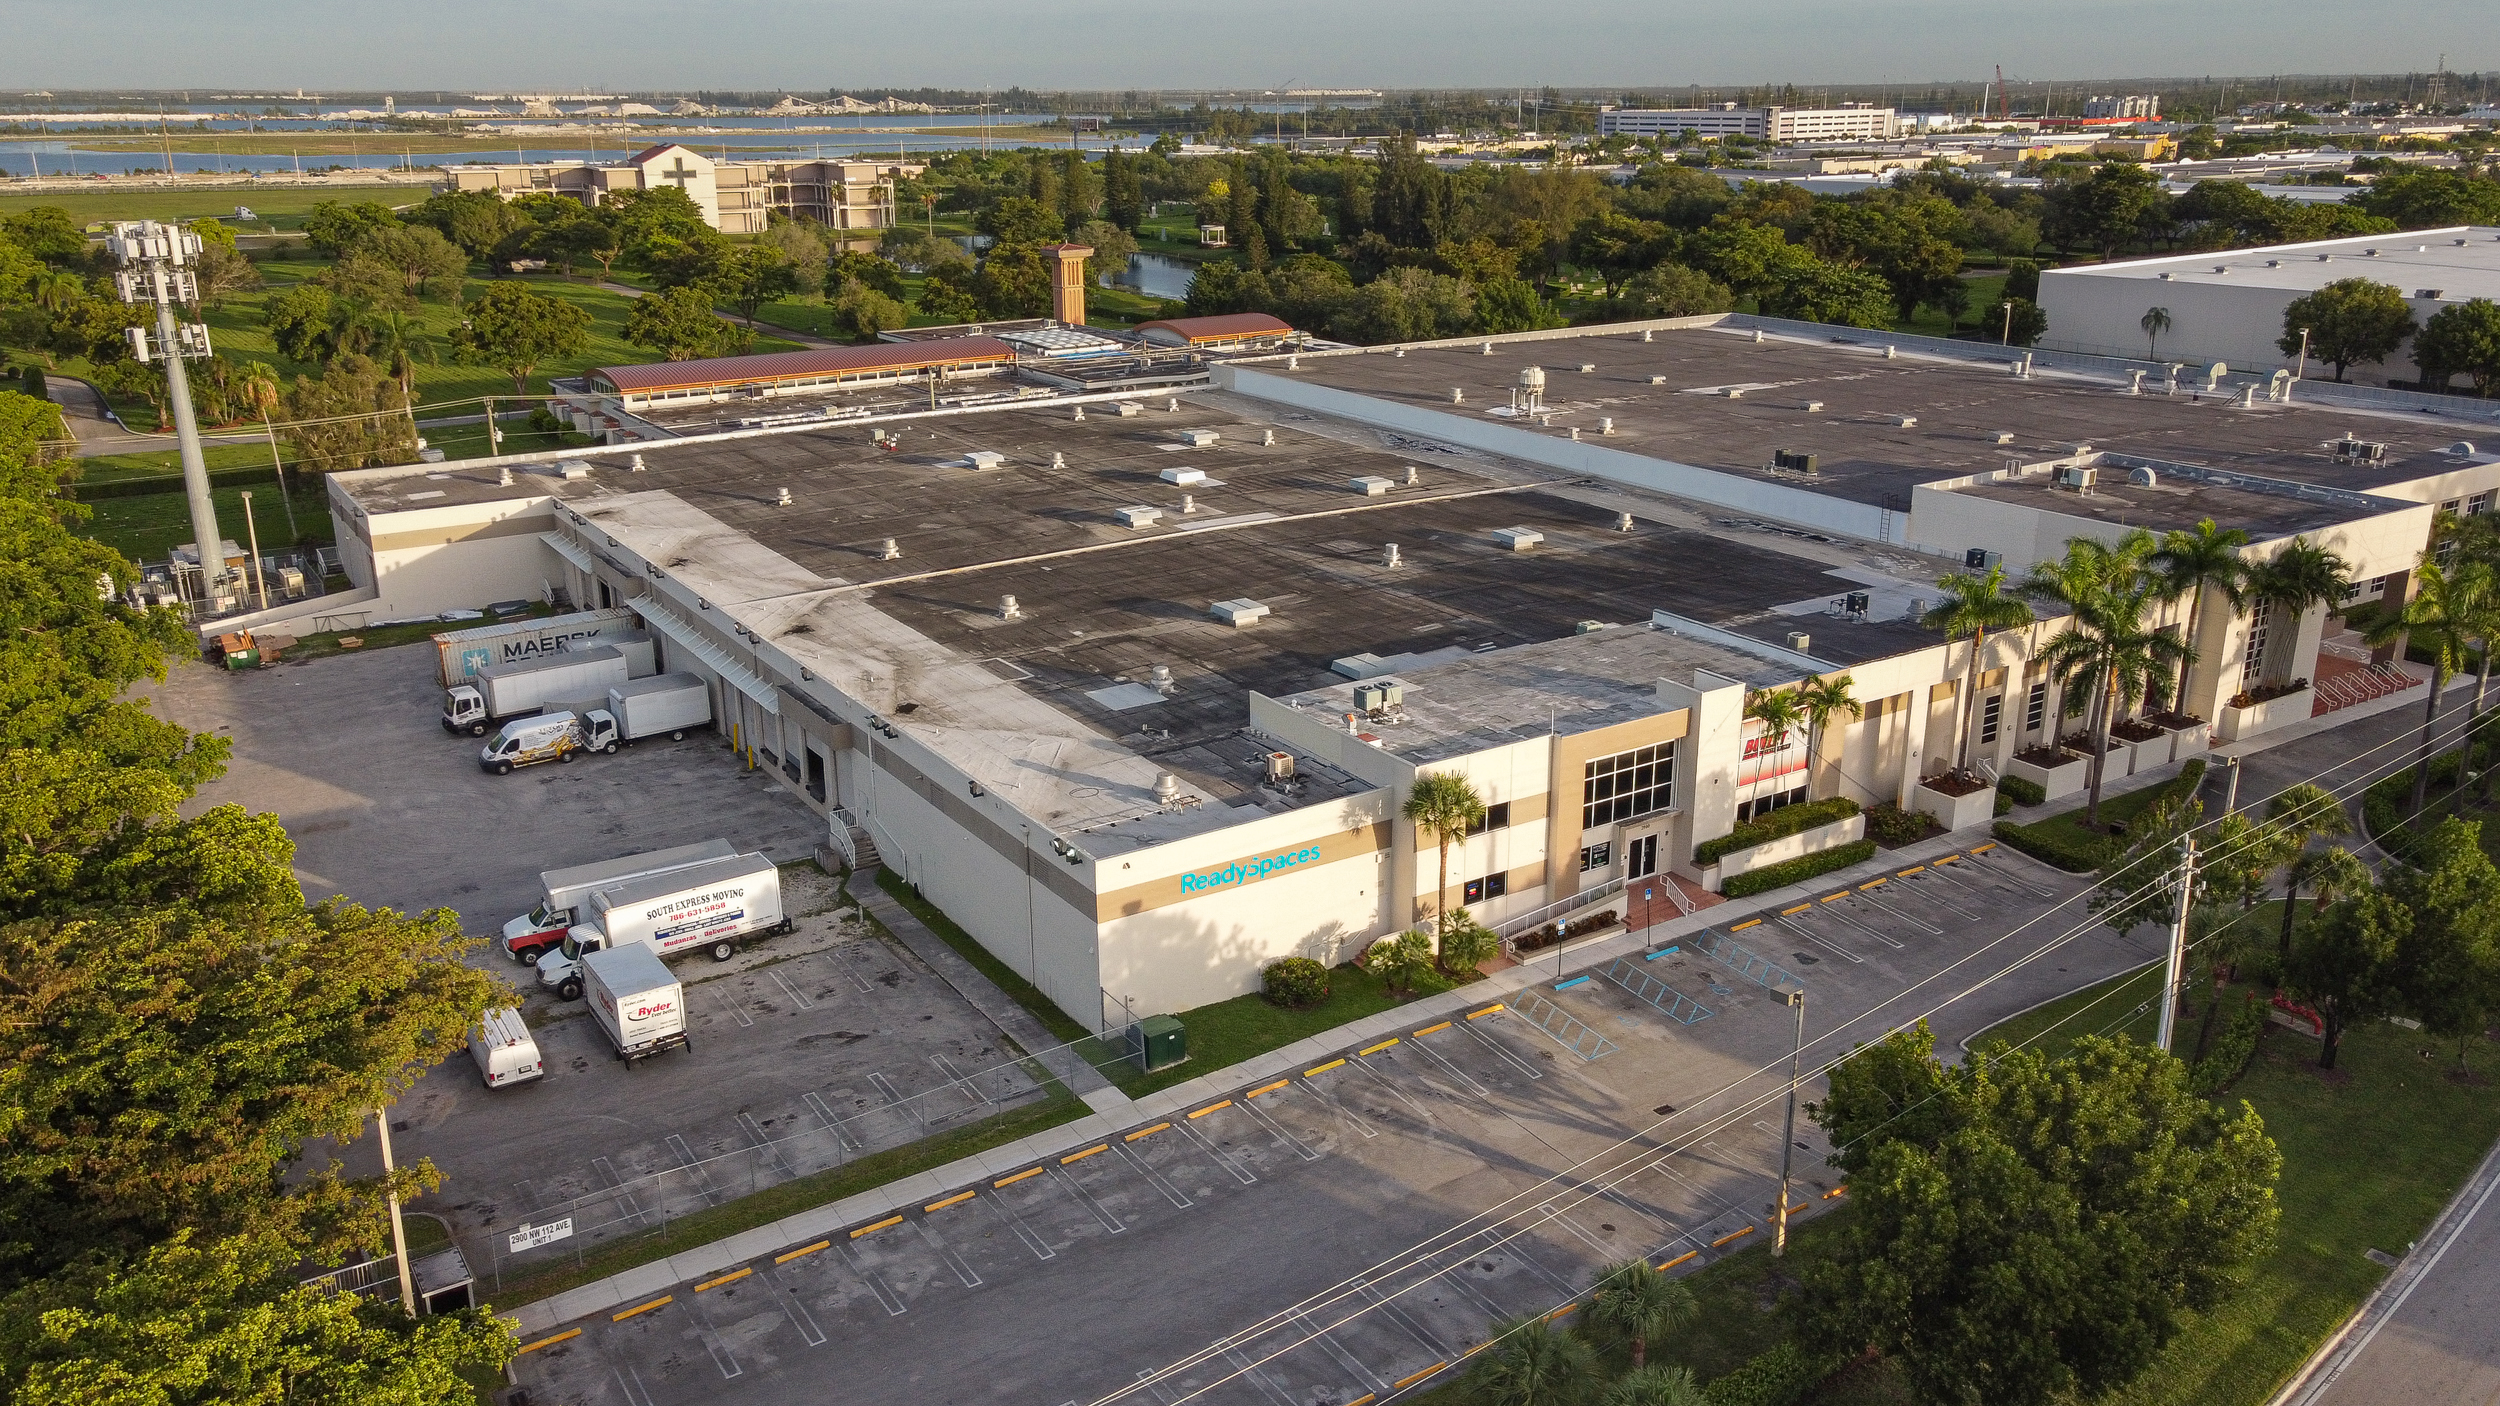
Phoenix Industrial & Warehouse Market Report | Q2 2026
Key Takeaways
- Phoenix industrial vacancy fell to 10.8% in Q2 2026, down 90 basis points from the restated prior quarter and 240 basis points year over year. The metro absorbed 6.1 million SF across a 450.4 million SF inventory.
- Overall asking rents rose 3.1% on the quarter to $1.12/SF/month NNN ($13.41/SF/year) but remain below their Q2 2025 level. Direct asking rents reached $1.15/SF/month. Cushman & Wakefield quotes Phoenix rents on a monthly NNN basis.
- The Southwest Valley absorbed 5.1 million SF of the metro’s 6.1 million SF total, with 9.3% vacancy and rents of $0.91/SF/month. The Northeast Valley is the tightest submarket at 7.3%, followed by the Northwest Valley at 7.7%, while the Southeast Valley has the highest vacancy at 16.4%.
- The construction pipeline grew to 16.0 million SF from 10.4 million SF in the prior quarter, and 59% of it is speculative. Deliveries total 3.8 million SF year to date. Browse Phoenix warehouse listings on WareCRE.
10.8%
Overall Vacancy
$1.12
Avg. Asking Rent (NNN/SF/Mo)
6.1M
SF Absorbed (Q2 2026)
16.0M
SF Under Construction
Phoenix’s industrial market tightened again in Q2 2026. Net absorption of 6.1 million SF, nearly double Q1’s restated 3.2 million SF, pulled overall vacancy down to 10.8%. That is 90 basis points lower than in Q1 and 240 basis points lower than a year ago. Warehouse and distribution product accounted for 96% of the quarter’s absorption, so the recovery rests on bulk logistics demand.
Two things complicate the headline for occupiers. Demand is highly concentrated, with the Southwest Valley alone absorbing 5.1 million SF of the 6.1 million SF total. The construction pipeline also jumped from 10.4 million SF to 16.0 million SF, 59% of it speculative. For businesses looking for warehouse space in Phoenix, submarket and building size will shape their options more than the metro average.
Market Snapshot: Q2 2026
| Metric | Q2 2026 | Change |
|---|---|---|
| Overall vacancy | 10.8% | ↓90 bps QoQ (11.7% in Q1, restated); ↓240 bps YoY |
| Overall asking rent | $1.12/SF/mo NNN | +3.1% QoQ; $13.41/SF/year vs. $13.01 in Q1 (restated) |
| Direct asking rent | $1.15/SF/mo NNN | Up quarter over quarter |
| Net absorption | 6.1M SF | Up from 3.2M SF (Q1 restated); 96% warehouse/distribution |
| Leasing activity | 7.7M SF | +2.1% QoQ from 7.5M SF; 15.2M SF year to date |
| Under construction | 16.0M SF | 59% speculative; up from 10.4M SF |
| Deliveries | 3.8M SF YTD | Year-to-date basis; no quarter-only figure published |
| Total inventory | 450.4M SF | Base for all vacancy and absorption figures above |
Figures are from Cushman & Wakefield’s Q2 2026 Phoenix Industrial MarketBeat. Q1 2026 comparisons use the values as restated in its Q2 2026 U.S. national tables, which also give the annual rent equivalents. Rents are NNN asking rates quoted per month, the Cushman & Wakefield convention for Phoenix; multiply by twelve to compare them with markets quoted per year.
Rent Trends: Up on the Quarter, Still Below a Year Ago
Overall asking rents reached $1.12/SF/month NNN ($13.41/SF/year), up 3.1% from the prior quarter’s restated $13.01/SF/year. Direct asking rents, which exclude sublease space, rose to $1.15/SF/month NNN. Both remain below their Q2 2025 levels. The small gap between overall and direct rents suggests sublease space is not setting market pricing.
Rents vary widely across the metro. Big-box bulk product in the Southwest Valley asks $0.91/SF/month, against $1.47 in the Northeast Valley, $1.20 in the Southeast Valley, $1.19 in the Northwest Valley and $1.13 in the Airport submarket. Asking rents rose in all five submarkets in Q2, from 0.8% in the Northwest Valley to 6.6% in the Southeast Valley. The largest, most outlying space is the cheapest per SF, and infill and mid-box product carries the premium. Occupiers who shop on cost per SF alone will default to the Southwest Valley, which may not suit their drive-time needs.
For Tenants
Tenant leverage in Phoenix depends on the submarket. At 16.4% vacancy, the Southeast Valley is the metro’s clearest tenant’s market and its deepest pool of smaller units. The Northeast and Northwest Valleys, at 7.3% and 7.7%, offer the least room to negotiate. The 16.0 million SF pipeline, 59% of it speculative, should keep adding big-box options through 2027, mostly in the Southwest and Southeast Valleys. Browse Phoenix warehouse listings on WareCRE.
Construction: Pipeline Jumps but Stays Below Its Recent Average
Phoenix has 16.0 million SF under construction, up from 10.4 million SF in the prior quarter, with 59% of that space speculative. That was the largest increase in groundbreakings since Q3 2022, but the pipeline remains well below its 2022–2025 quarterly average of 30.0 million SF. Deliveries total 3.8 million SF year to date, well below the 9.4 million SF of net absorption over the same period, which is why vacancy fell even as the pipeline grew.
Absorption of 6.1 million SF in a quarter comfortably clears the current delivery pace, but the pipeline will reach the market over the next several quarters. Vacancy keeps compressing only if demand holds near the Q2 pace rather than slipping back toward the prior quarter’s 3.2 million SF.
For Operators
A 240 basis point drop in vacancy over the year and 3.1% quarterly rent growth support holding rate on stabilized warehouse and distribution product. The risk is the 16.0 million SF pipeline, 59% of it speculative. Southeast Valley owners face the metro’s highest vacancy, 16.4%, and its most fragmented demand, with roughly 200 leases year to date averaging 14,298 SF. Lease-up there depends on steady small-deal volume.
Submarket Breakdown: Southwest Valley Carried the Quarter
Southwest Valley
The Southwest Valley absorbed 5.1 million SF of the 6.1 million SF metro total in Q2 2026. At 204.7 million SF, it is the largest submarket and the center of big-box bulk distribution. Vacancy fell 660 basis points year over year to 9.3%, and overall asking rents of $0.91/SF/month NNN are the lowest in the metro. DHL’s 1.18 million SF lease at Northern Parkway Logistics Center, the quarter’s largest, was signed here. Deals run large, with roughly 100 leases year to date averaging 94,423 SF.
Southeast Valley
The Southeast Valley has the metro’s highest vacancy at 16.4%, though that is down 70 basis points on the year. Overall asking rents of $1.20/SF/month NNN are second only to the Northeast Valley’s. Advanced manufacturing and the EV supply chain anchor demand, and LG Energy Solution’s 1.5 million SF owner-user project is among the metro’s largest under construction. Small tenants concentrate here, with roughly 200 leases year to date averaging 14,298 SF.
Airport
The Airport submarket is Phoenix’s infill, last-touch market, with 69.9 million SF at 10.3% vacancy and $1.13/SF/month NNN asking rents. It gave back 234,677 SF of occupancy in Q2, the largest loss of any submarket. Its central location still draws tenants that serve the metro population rather than a regional distribution area.
Northwest Valley
The Northwest Valley is the metro’s second-tightest submarket at 7.7% vacancy, behind the much smaller Northeast Valley at 7.3%, with asking rents of $1.19/SF/month NNN. It absorbed 156,575 SF in Q2 with no deliveries this year, and 2.7 million SF is under construction.
| Submarket | Vacancy | Asking Rent (NNN/SF/Mo) | Q2 2026 Profile |
|---|---|---|---|
| Southwest Valley | 9.3% | $0.91 | 204.7M SF; big-box bulk; absorbed 5.1M SF |
| Southeast Valley | 16.4% | $1.20 | Highest vacancy; advanced mfg and EV supply chain |
| Airport | 10.3% | $1.13 | 69.9M SF; infill last-touch; gave back 234,677 SF |
| Northwest Valley | 7.7% | $1.19 | Second-tightest after Northeast Valley; 2.7M SF under construction |
Co-Warehousing & Flexible Warehouse Space in Phoenix
Small-tenant demand in Phoenix is concentrated in one part of the Valley. The Southeast Valley signed roughly 200 leases year to date at an average of 14,298 SF, while the Southwest Valley signed roughly 100 at an average of 94,423 SF. By deal count the Southeast Valley is a small-bay and mid-bay market; by square footage the Southwest Valley is a big-box one.
For smaller occupiers, the Southeast Valley is where small-format leasing is most active, and its 16.4% vacancy gives them unusual negotiating room for a growing metro. Advanced manufacturing and EV supply chain activity there also generates steady vendor, staging and overflow requirements that suit co-warehousing and small-bay space better than a bulk distribution box.
Browse available co-warehousing and small-bay listings on WareCRE’s Phoenix marketplace.
Looking for warehouse space in Phoenix?
Key Trends to Watch
1. Bulk Logistics Is Carrying the Recovery
Warehouse and distribution product accounted for 96% of Q2 2026 net absorption. That is a narrow base for a 6.1 million SF quarter, and it ties the metro’s vacancy path to bulk logistics demand. The quarter’s two largest leases, DHL’s 1.18 million SF at Northern Parkway Logistics Center and Fluidstack’s 1.15 million SF at Luke Field, were both in the Southwest Valley. Cushman & Wakefield expects large recent leases to support absorption through the rest of 2026. For national context, see How Tariffs Are Reshaping Warehouse Demand in 2026.
2. Demand Is Concentrated in One Submarket
The Southwest Valley absorbed 5.1 million SF of the metro’s 6.1 million SF. The Southeast Valley added another 1.2 million SF, while the Airport and Northeast Valley submarkets both lost occupancy. The metro vacancy rate of 10.8% is accurate but a poor guide to any single corridor, where vacancy runs from 7.3% in the Northeast Valley to 16.4% in the Southeast Valley.
3. The Small-Bay and Big-Box Split Runs Along Submarket Lines
Phoenix’s size split follows geography. The Southeast Valley averaged 14,298 SF per lease year to date across roughly 200 leases, and the Southwest Valley averaged 94,423 SF across roughly 100. A tenant near the Southeast Valley average is shopping a different market from one near the Southwest Valley average, with different vacancy, pricing and landlords. See Small-Bay vs. Big-Box: What the Vacancy Gap Means.
4. The Pipeline Jumped as the Speculative Share Fell
Under construction volume rose from 10.4 million SF to 16.0 million SF in a single quarter, yet the speculative share fell to 59%, the lowest since at least 2022. Cushman & Wakefield reads this as developers staying measured, given elevated vacancy and limited rent growth, while build-to-suit activity rises as large occupiers seek newer facilities. With 3.8 million SF delivered year to date, most of that pipeline has yet to land.
Outlook: What to Watch in Q4 2026
Phoenix closed the first half of 2026 with real momentum and a visible supply risk. Vacancy has fallen 240 basis points year over year, absorption nearly doubled quarter over quarter, and leasing reached 15.2 million SF year to date. Cushman & Wakefield expects vacancy to keep compressing in the near term. The pipeline is the counterweight.
Vacancy depends on whether absorption holds. At the Q2 pace of 6.1 million SF a quarter, the metro can absorb the 16.0 million SF pipeline comfortably. At the prior quarter’s 3.2 million SF pace, the 59% speculative share becomes a vacancy risk as it delivers, more likely in 2027 than in 2026.
Expect rent growth to stay uneven. Overall asking rents grew 3.1% on the quarter to $1.12/SF/month, but pricing decisions happen within a submarket spread of $0.91 to $1.47. Owners in the Northeast Valley (7.3% vacancy) and the Northwest Valley (7.7%) have the least reason to concede.
Watch the Airport submarket. It gave back 234,677 SF in Q2 while the metro absorbed 6.1 million SF, and it has lost occupancy in both quarters of 2026, roughly 607,000 SF year to date. A third straight negative quarter would signal weak demand for infill, last-touch space, which is a different problem from big-box oversupply. It is the reading most worth tracking into Q4.
Find warehouse space in Phoenix
Browse co-warehousing, small-bay, and flex listings across the Phoenix metro.
Data sources: Cushman & Wakefield Phoenix Industrial MarketBeat Q2 2026 (metro rents quoted monthly NNN) and U.S. Industrial MarketBeat Q2 2026 (restated Q1 2026 comparisons); Kidder Mathews Phoenix 2Q26 (11.4% total vacancy and $1.18/SF/month NNN direct asking for spaces of 10,000 SF and up, on an inventory base roughly 15 million SF larger, so the two series are not directly comparable); WareCRE marketplace data. Each report reflects the most recent vacancy, rental, and construction data available at the time of publication. We refresh our reports as new market data is released, and we’re continually expanding coverage to additional metros.
Related Resources
Frequently Asked Questions
What is the current industrial vacancy rate in Phoenix?
Phoenix industrial vacancy is 10.8% as of Q2 2026 per Cushman & Wakefield, down 90 basis points from Q1 (as restated) and 240 basis points year over year. Submarket vacancy ranges from 7.3% in the Northeast Valley to 16.4% in the Southeast Valley, so the metro figure is a poor proxy for conditions in any single corridor.
How much does warehouse space cost in Phoenix?
Overall asking rents are $1.12/SF/month NNN as of Q2 2026 ($13.41/SF/year), up 3.1% on the quarter. Direct asking rents are $1.15/SF/month. By submarket, rents run from $0.91/SF/month in the Southwest Valley to $1.47 in the Northeast Valley, with the Southeast Valley at $1.20, the Airport submarket at $1.13 and the Northwest Valley at $1.19. Cushman & Wakefield quotes Phoenix on a monthly NNN basis.
Which Phoenix submarket is best for warehouse space?
It depends on size. The Southwest Valley is the big-box market, 204.7 million SF of mostly bulk distribution at 9.3% vacancy and the metro’s lowest rents of $0.91/SF/month. The Southeast Valley suits smaller requirements, averaging 14,298 SF per lease year to date with the metro’s highest vacancy at 16.4%. The Airport submarket serves infill and last-touch users, and the Northeast Valley is the tightest at 7.3%, followed by the Northwest Valley at 7.7%.
How much industrial space is under construction in Phoenix?
Phoenix has 16.0 million SF under construction as of Q2 2026, up from 10.4 million SF the prior quarter, and 59% of it is speculative. Deliveries total 3.8 million SF year to date against 9.4 million SF of year-to-date net absorption, which is why vacancy fell even as the pipeline grew. That pipeline is the main risk to further vacancy compression if absorption slows from its Q2 pace.