Seattle Industrial & Warehouse Market Report | Q3 2026
Key Takeaways
- Puget Sound industrial vacancy rose to 10.2% in Q3 2026 from 9.4% in Q2 on Cushman & Wakefield’s basis, up 140 basis points from a year earlier. Kidder Mathews, on a wider inventory, puts vacancy at 9.7% and stabilizing.
- Vacancy rose on speculative deliveries, tenant consolidations and several large move-outs, and net absorption swung to −1,210,751 SF in Q3 from +888,602 SF in Q2 (restated). Leasing rose 31.8% year over year to 2.2 million SF.
- Asking rents were flat. Kidder Mathews put the blended Puget Sound rate at $1.06/SF NNN per month (about $12.72/SF per year), unchanged from Q2.
- The pipeline shrank to just under 1.3 million SF, while 1.1 million SF delivered in Q3, all of it vacant. Brokers report rising demand for large blocks of 300,000 to 700,000 SF. Browse Seattle warehouse listings on WareCRE.
10.2%
Overall Vacancy (Q3 2026)
$1.06
Blended Asking Rent (NNN/SF/Mo)
−1.2M
SF Net Absorption (Q3)
1.3M
SF Under Construction
Seattle and the broader Puget Sound region form one of the West Coast’s most important industrial markets. It is a Pacific gateway anchored by the Northwest Seaport Alliance (the ports of Seattle and Tacoma) and hemmed in by water, mountains and tight land supply. On Cushman & Wakefield’s numbers, fundamentals softened again in Q3 2026. Vacancy edged above 10% to 10.2%, net absorption turned negative at 1.2 million SF, and 1.1 million SF of new space delivered vacant across a 270.8 million SF inventory base.
The statistics lag the mood. C&W says brokers report noticeably healthier leasing fundamentals than the numbers suggest, with more proposals and renewed interest in large blocks, and Kidder Mathews shows vacancy stabilizing at 9.7%. For businesses looking for warehouse space in Seattle, the market still favors tenants, especially on large requirements, while small-bay space is where most of the deals and the competition are.
Market Snapshot: Q3 2026
| Metric | Q3 2026 | Context |
|---|---|---|
| Overall vacancy | 10.2% | ↑80 bps from 9.4% in Q2 (restated); ↑140 bps YoY per C&W’s Seattle report (national table: 8.6% a year earlier, +160 bps) |
| Blended asking rent | $1.06/SF NNN/mo | About $12.72/SF/yr; flat QoQ (Kidder Mathews) |
| Net absorption (Q3) | −1,210,751 SF | After +888,602 SF in Q2 (restated); −658,584 SF year to date |
| Leasing activity (Q3) | 2.2M SF | +31.8% YoY; 6.3M SF year to date vs. 7.1M SF a year earlier |
| Deliveries (Q3) | 1.1M SF | Three projects, 100% vacant; just under 2.9M SF year to date |
| Under construction | 1.3M SF | Four projects; 14.4M SF more proposed |
| Total inventory | 270.8M SF | Cushman & Wakefield basis; Kidder Mathews tracks 410.9M SF over a wider geography |
Vacancy levels differ by source because each tracks a different geography and inventory base. Cushman & Wakefield reports 10.2% after 1.2 million SF of negative absorption, while Kidder Mathews shows 9.7% with about 401,000 SF of positive absorption. Both show vacancy higher than at the end of 2025.
Rent Trends: $1.06/SF/mo Blended, Flat on the Quarter
Kidder Mathews put the blended Puget Sound asking rate at $1.06/SF NNN per month in Q3 2026, or about $12.72/SF per year, the same as in Q2. Pacific Northwest industrial space is quoted monthly on an NNN basis, so the monthly figure is the one used in negotiations. This page follows the Kidder Mathews series; Cushman & Wakefield’s narrower series puts the Q3 average at $1.04, up 8.3% from a year earlier.
Landlords are holding face rates and competing on concessions and creative lease structures. C&W also describes “space pocketing,” where tenants commit to large blocks but phase occupancy over time. It says landlords’ focus on protecting occupancy may allow rents to creep down in the coming quarters, and Kidder Mathews shows Seattle Close-In blended rents down from $1.43 in Q1 to $1.33 in Q3.
For Tenants
Tenants hold the leverage, especially on big blocks. Vacancy is above 10% on C&W’s measure, all 1.1 million SF delivered in Q3 arrived vacant, and landlords are offering concessions and phased occupancy to win deals. Negotiate free rent, improvement allowances and term flexibility, since face rates are not moving. Small spaces remain the most active segment in Seattle Close-In, so smaller users should expect more competition. Search Seattle warehouse listings on WareCRE.
Construction Pipeline: Down to 1.3 Million SF
Puget Sound had just under 1.3 million SF under construction at the end of Q3 2026 across four projects, per Cushman & Wakefield, with another 14.4 million SF proposed. More than 1.1 million SF delivered in Q3 across three projects, all of it vacant, bringing the year-to-date total to just under 2.9 million SF. C&W says new projects struggle to break ground given leasing risk, financing costs and higher vacancy, and expects the reduced supply to help stabilize vacancy over the coming years.
Kidder Mathews counts 1.36 million SF underway, 80.2% of it in the Southend, a shift away from Pierce County. Pierce delivered nine buildings totaling 2.8 million SF this year and now has the highest vacancy in Puget Sound at 13.2%. The Port of Seattle’s 405,680 SF Des Moines Creek West is due by year-end, and Shield AI has leased the full building.
For Operators
Protect occupancy over rate. Absorption turned sharply negative in C&W’s figures, new speculative buildings are delivering vacant, and C&W expects limited rent growth while pricing power stays with occupiers. The offset is demand: brokers report more proposals and stronger interest in 300,000 to 700,000 SF blocks, and Kidder Mathews counted nine leases over 100,000 SF in Q3. Small-bay space, especially close in, remains the most active part of the market.
Submarket Breakdown: Auburn at 4.1% Vacancy, Kent and Sumner Above 10%
Kent
Kent is the region’s largest submarket at 48.9 million SF and the core of Kent Valley big-box distribution. Vacancy rose to 11.0% in Q3 2026 as the submarket gave back 426,199 SF, reflecting its concentration of large available blocks. A big requirement will find more competing options here than anywhere else in Puget Sound, at $0.92/SF NNN per month.
South Seattle
South Seattle is the close-in infill core, nearest the Port of Seattle and the urban consumer base. Vacancy was 9.2%, and at $1.33/SF NNN per month it is the priciest of the four Cushman & Wakefield submarkets profiled here. Kidder Mathews puts the overlapping Seattle Close-In submarket at 9.8% vacancy and $1.33/SF NNN per month; its largest vacancy is still the 702,429 SF Seattle Metro Logistics on Port of Seattle land.
Sumner
Sumner is a Pierce County bulk-distribution submarket, asking $0.97/SF NNN per month with vacancy at 12.7%, the highest of the four. It gave back 56,305 SF in Q3 but is still positive at 280,651 SF year to date.
Auburn
Auburn is the tightest of the four at 4.1% vacancy, a landlord’s market inside an otherwise soft region, though it gave back 150,292 SF in Q3. Among the larger submarkets, only Renton, at 3.4%, is tighter. Tenants targeting Auburn should expect few alternatives and little negotiating room.
| Submarket | Vacancy (Q3 2026) | Asking Rent (Q3 2026, NNN/SF/Mo) | Q3 2026 Profile |
|---|---|---|---|
| Kent | 11.0% | $0.92 | Largest submarket (48.9M SF); core Valley big-box; lowest rent of the four |
| South Seattle | 9.2% | $1.33 | Close-in infill; priciest of the four |
| Sumner | 12.7% | $0.97 | Pierce County bulk; highest vacancy of the four |
| Auburn | 4.1% | $0.96 | Tightest of the four |
Vacancy and asking rents above are Cushman & Wakefield Q3 2026 (overall weighted net asking rent, $/SF/mo). Across the Cushman & Wakefield Puget Sound submarkets, Q3 asking rents run from $0.60 in Lacey to $1.75 in University Place. The Kidder Mathews view below uses different submarket definitions.
| Kidder Mathews Submarket | Vacancy (Q3 2026) | Asking Rent (Q3 2026, NNN/SF/Mo) |
|---|---|---|
| Eastside | 6.1% | $1.79 |
| Seattle Close-In | 9.8% | $1.33 |
| Southend | 10.3% | $1.11 |
| Pierce | 13.2% | $0.80 |
| Thurston | 4.6% | $0.86 |
The two tables use different submarket definitions and inventory bases (Kidder Mathews also covers the Eastside, the Northend, and Skagit and Whatcom counties, which the Cushman & Wakefield table omits), so read them as complementary views of the region.
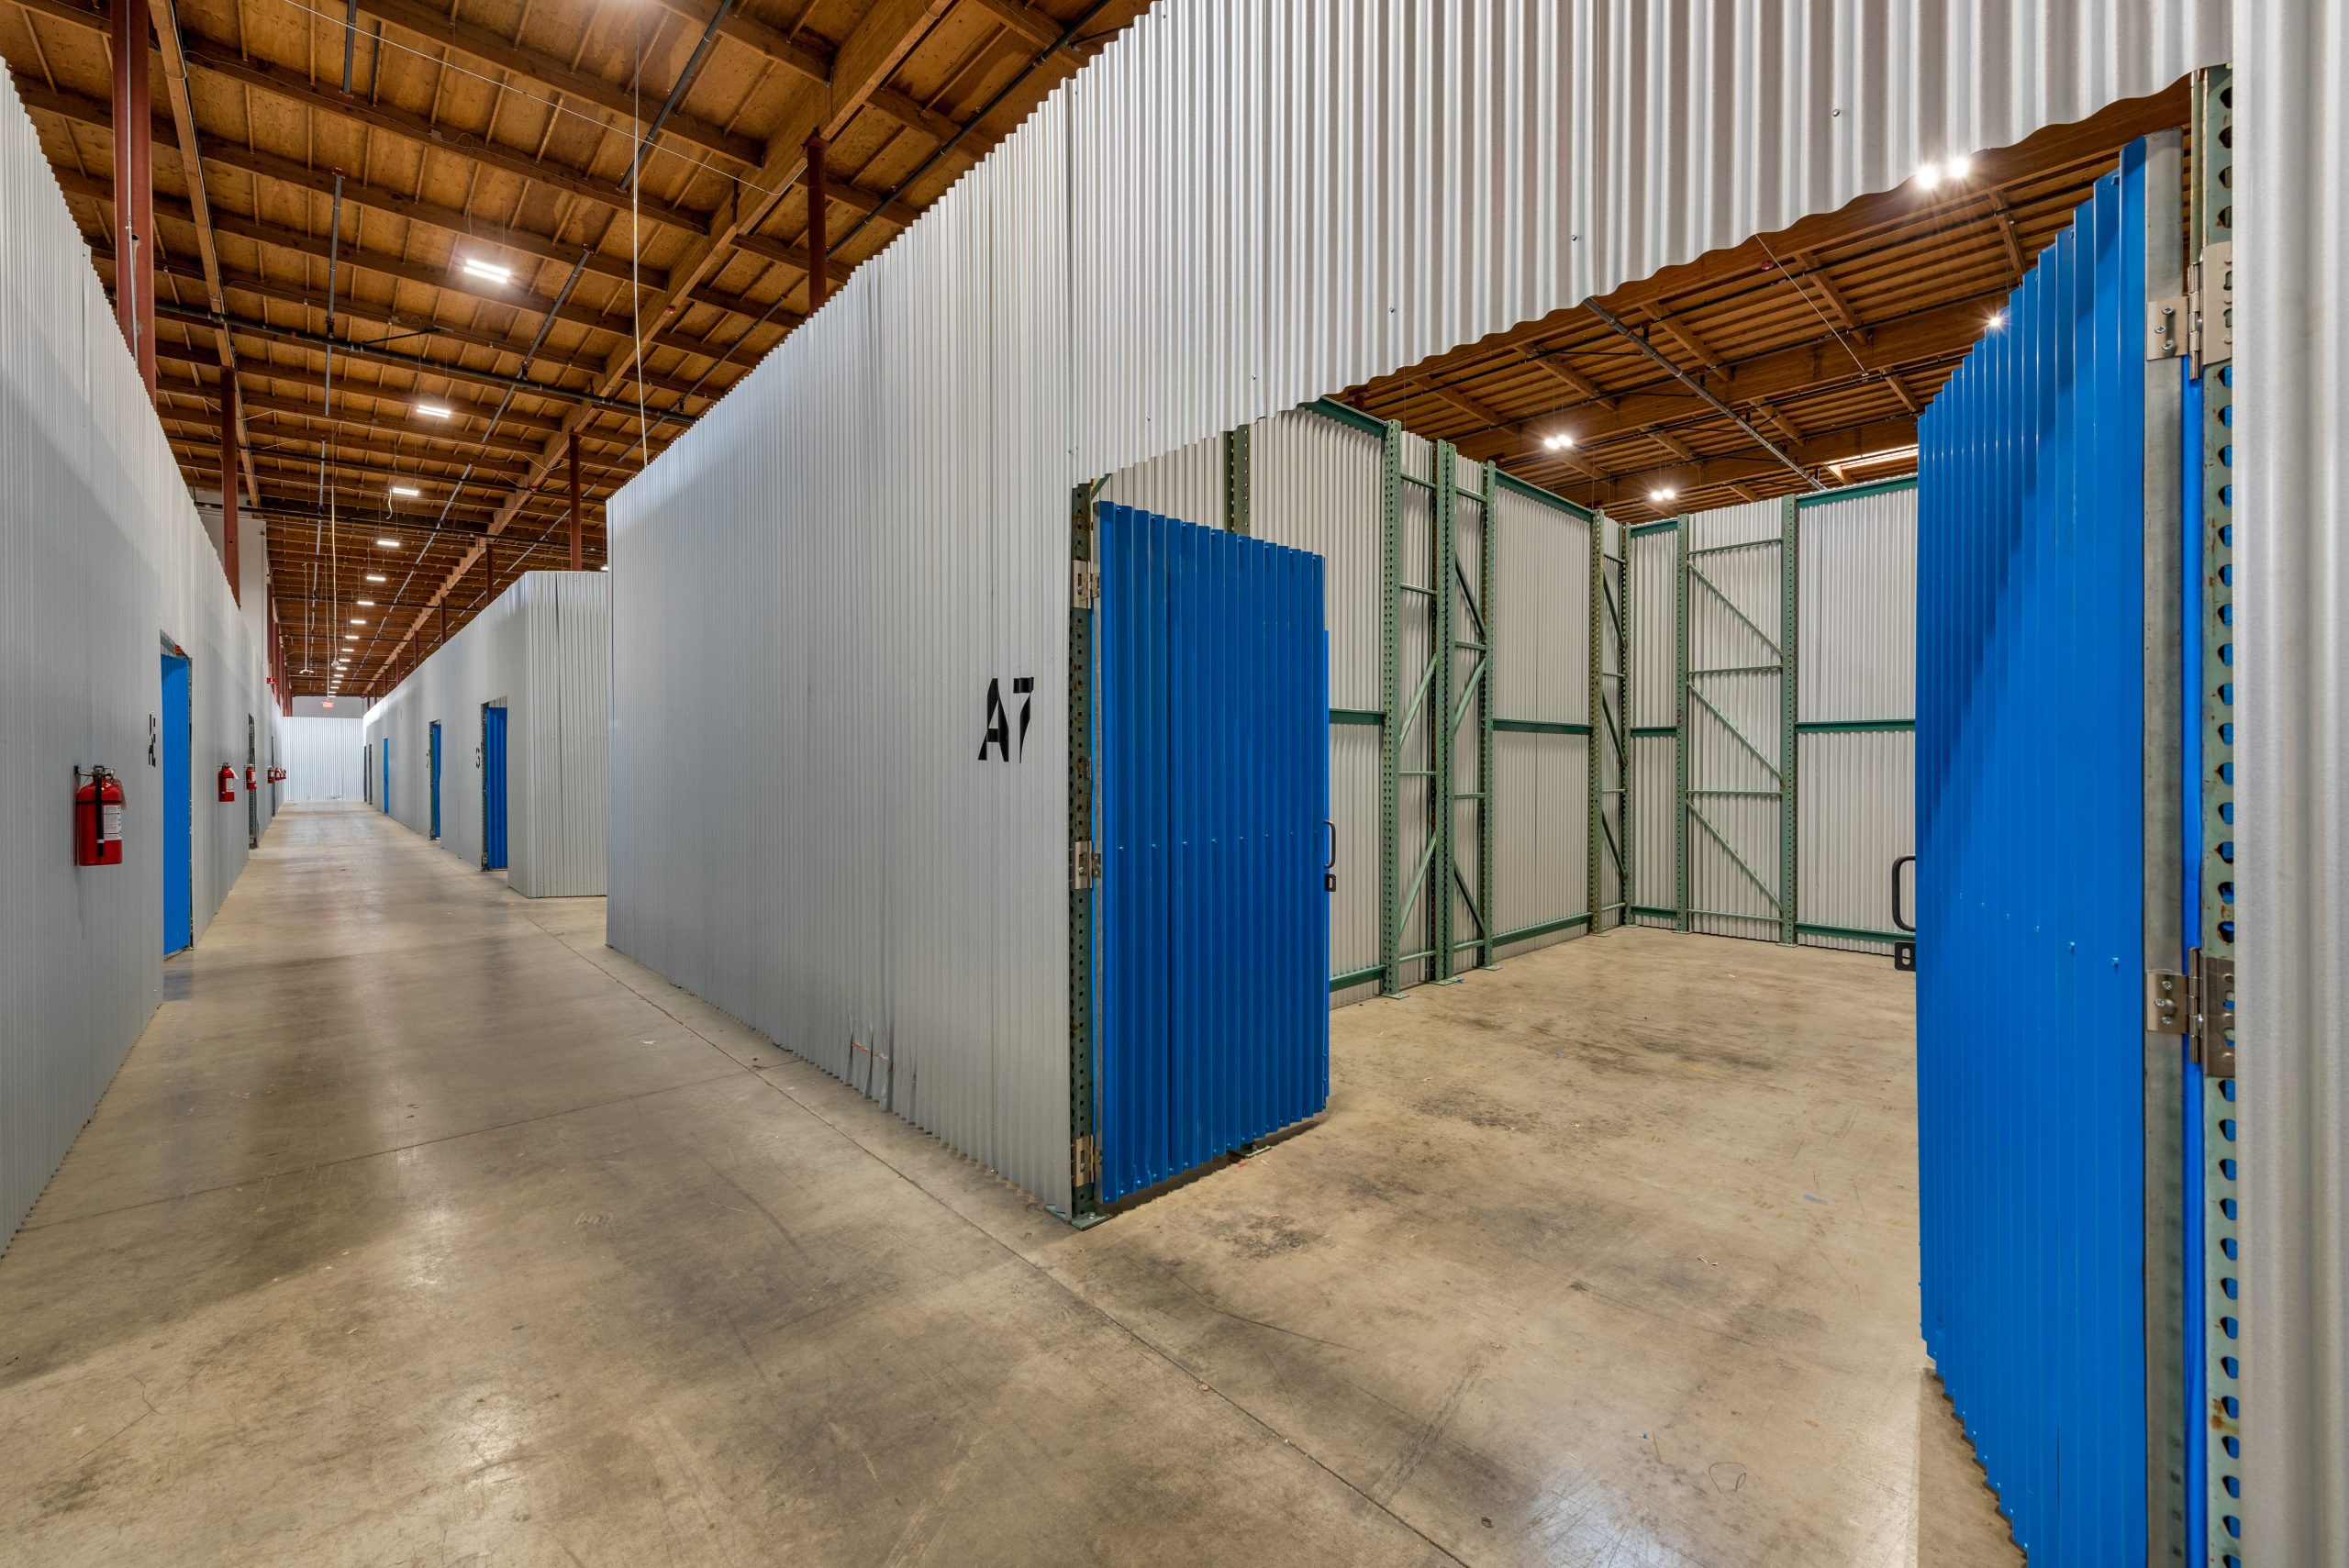
Co-Warehousing & Flexible Warehouse Space in Seattle
Small-bay deals make up most of the market’s transactions. Kidder Mathews reports Q3 median lease sizes of 2,692 SF in Thurston County, 3,026 SF on the Eastside and 16,521 SF in the Southend, and says spaces under 10,000 SF remain the most active in Seattle Close-In.
Close-in supply at that size is deep. Kidder Mathews counts 109 available spaces between 5,000 and 10,000 SF in Seattle Close-In, plus 107 in the 10,000 to 25,000 SF band, giving smaller users real choice inside the urban core at about $1.33/SF NNN per month.
Flexible-space demand in Seattle comes mostly from last-mile and e-commerce operators that need to sit close to urban customers, and from contractors and building trades. Food and beverage makers, importers and 3PLs using the Northwest Seaport Alliance gateway, and growing businesses that want space without a long big-box lease make up the rest.
Browse available co-warehousing and small-bay warehouse listings on WareCRE’s Seattle marketplace.
Looking for warehouse space in Seattle?
Key Trends to Watch
1. Big-Block Demand Is Returning, but Absorption Lags
Brokers report noticeably healthier leasing than the statistics show, with lease proposals up and occupiers re-entering the market. Demand for 300,000 to 700,000 SF blocks has improved significantly, and advanced manufacturing and aerospace users have the most active requirements. Kidder Mathews counted nine leases over 100,000 SF in Q3, totaling nearly 2.1 million SF, including Shield AI’s 405,680 SF at Des Moines Creek Business Park West and 265,922 SF at Prologis Park SeaTac 3. Deals like Shield AI’s, which is projected to commence in March 2027, will not show up as absorption until tenants move in.
2. Small-Bay and Big-Box Space Are Moving at Different Speeds
Median lease sizes run from 2,692 SF in Thurston County to 16,521 SF in the Southend, and small spaces are the most active segment close in, while C&W says renewals remain a large part of activity and often extend transaction timelines. Vacancy splits just as sharply by submarket, from 4.1% in Auburn to 12.7% in Sumner among the four profiled above. For the national picture, see Small-Bay vs. Big-Box: What the Vacancy Gap Means in 2026.
3. A 1.3 Million SF Pipeline Leaves Little New Supply Ahead
Q3’s speculative completions arrived vacant and still weigh on the market, but little product follows them. The pipeline is just under 1.3 million SF against 270.8 million SF of inventory, and C&W calls the slowdown a positive long-term catalyst that should let organic growth absorb existing space. With chronic land scarcity and exposure to Pacific trade flows, the market could tighten quickly once large-user demand converts to occupancy. For broader context, see Industrial Real Estate Trends & Outlook 2026 and, on trade policy, How Tariffs Are Reshaping Warehouse Demand in 2026.
Outlook: What to Watch in Early 2027
Cushman & Wakefield’s Q3 numbers weakened, while Kidder Mathews shows vacancy stabilizing. Both describe a market where leasing sentiment is improving faster than the statistics.
Vacancy direction. C&W expects vacancy to stay high in the near term, with demand supporting gradual stabilization. Only 1.3 million SF is under construction, so the next readings depend on whether the large leases signed in Q3 turn into move-ins.
Rent direction. Watch whether rents stay flat. At $1.06/SF NNN per month blended and with vacancy near 10%, C&W expects rent growth to stay limited while pricing power remains with occupiers. For now, landlords compete through concessions.
Deal size. Kidder Mathews counted nine leases over 100,000 SF in Q3. If that pace holds and the deals commence, absorption should turn positive on C&W’s measure as well. Until then, tenants with large requirements hold the leverage.
Find warehouse space in Seattle
Browse co-warehousing, small-bay, and distribution listings across the Puget Sound region.
Data sources: Cushman & Wakefield Seattle MarketBeat Q3 2026 (vacancy, absorption, leasing, deliveries, construction, inventory, submarket vacancy and rents) and U.S. Industrial MarketBeat Q3 2026 (restated Q2 figures); Kidder Mathews Seattle 3Q26 (blended asking rent, submarket, lease-size and large-lease data); WareCRE marketplace data. The headline asking rent follows the Kidder Mathews series; vacancy, absorption, supply and the first submarket table follow Cushman & Wakefield. Source inventory bases differ (Cushman & Wakefield 270.8M SF, Kidder Mathews 410.9M SF), so figures are not directly interchangeable.
Related Resources
Frequently Asked Questions
What is the current industrial vacancy rate in Seattle?
Puget Sound industrial vacancy was 10.2% in Q3 2026 on the Cushman and Wakefield basis, up from 9.4% in Q2 and 140 basis points higher than a year earlier. Kidder Mathews, which tracks a wider 410.9 million SF inventory, reports 9.7% and describes vacancy as stabilizing.
How much does warehouse space cost in Seattle?
Puget Sound industrial space is quoted monthly on an NNN basis. The blended asking rate was $1.06/SF per month in Q3 2026, about $12.72/SF per year, per Kidder Mathews, unchanged from Q2. By Kidder Mathews submarket, Pierce was $0.80, Thurston $0.86, Southend $1.11, Seattle Close-In $1.33 and the Eastside $1.79 per SF per month.
Is Seattle a good market for warehouse tenants right now?
For large requirements, yes. Vacancy is above 10% on C&W’s measure, new buildings are delivering vacant, and landlords are offering concessions and phased occupancy, which supports negotiation on free rent, improvement allowances and term. Competition is rising for the best large blocks as demand returns, and small spaces close in remain the most active segment, so smaller users should expect a faster, more competitive process.
Which Seattle submarket is best for warehouse space?
It depends on size and budget. Kent is the largest submarket at 48.9 million SF with the deepest big-box inventory and 11.0% vacancy. Of the four profiled here, Sumner is the loosest at 12.7% vacancy and Auburn the tightest at 4.1%. Kent asks the least of the four at $0.92/SF per month, while Lacey is the cheapest Cushman and Wakefield submarket overall at $0.60. South Seattle, the close-in infill option, has 9.2% vacancy and the highest rent of the four. Kidder Mathews counts 109 available spaces between 5,000 and 10,000 SF in the overlapping Seattle Close-In area.