Toronto Industrial & Warehouse Market Report | Q3 2026
Key Takeaways
- GTA industrial vacancy was 5.0% in Q3 2026, up 10 basis points from 4.9% a year earlier, a change Cushman & Wakefield calls effectively flat. Net absorption slowed to 542,914 SF but stayed positive, extending just over two years of gains.
- The average net asking rent fell 0.8% to C$15.90/SF/yr, a four-year low and the tenth straight quarterly decline. The pace slowed from Q2’s 2.0% drop.
- New leasing moderated to 6.0 million SF, close to the ten-year third-quarter average, and year-to-date leasing reached an eight-year high of 23.6 million SF.
- 8.3 million SF is under construction, 78.7% of it speculative. Only 15.3% of Q3 deliveries were pre-leased, and 2026 completions are tracking well below the 13.4 million SF annual average of the past three years.
Browse warehouse space for rent in Toronto
5.0%
Overall Vacancy (Q3 2026)
C$15.90
Avg. Net Asking Rent (C$/SF/yr)
543K
SF Net Absorption (Q3 2026)
8.3M
SF Under Construction
The Greater Toronto Area’s industrial market treaded water in Q3 2026. Vacancy held near 5.0%, absorption slowed to 542,914 SF after 2.4 million SF in Q2, and rents slipped again to a four-year low. Building age explains much of the market. Buildings 30 years and older hold 49.2% of vacant space and buildings under 10 years another 28.8%, while mid-life stock is the tightest. GTA West still carries nearly all of the year’s demand, and GTA Central keeps losing occupancy as tenants trade up.
Figures are from Cushman & Wakefield’s Q3 2026 Toronto (GTA) Industrial MarketBeat unless noted. Prior-quarter comparisons use the changes stated in that report. Rents are average net asking rents in Canadian dollars per square foot per year (C$/SF/yr); additional rent (taxes, maintenance and insurance) is quoted separately. The GTA totals exclude Hamilton, which C&W reports alongside them.
Market Snapshot: Q3 2026
| Metric | Q3 2026 | Q2 2026 (as published) | YoY or note |
|---|---|---|---|
| Overall vacancy | 5.0% | 4.9% | +10 bps YoY from 4.9% in Q3 2025; C&W calls it effectively flat |
| Average net asking rent (C$/SF/yr) | C$15.90 | C$16.03 | −0.8% QoQ; −5.6% YoY; lowest in four years |
| Additional rent (C$/SF/yr) | C$4.45 | n/a | Gross rent C$20.35 |
| Net absorption | 542,914 SF | 2.4M SF | 4,163,889 SF year to date; 2.0% below the 2025 pace |
| New leasing | 6.0M SF | n/a | 23.6M SF year to date, an eight-year high |
| Deliveries | 1.7M SF | n/a | 3,982,050 SF year to date; Q3 deliveries 15.3% pre-leased |
| Under construction | 8,264,009 SF | n/a | 78.7% speculative; 2.5M SF due by year-end |
| Average asking sale price (C$/SF) | C$409.97 | n/a | Owner-user and investment pricing indicator |
| Inventory | 853.8M SF | n/a | Excludes Hamilton |
Source: Cushman & Wakefield, Toronto (GTA) Industrial MarketBeat Q3 2026; additional and gross rent from C&W’s Canada Industrial MarketBeat Q3 2026 table. Q2 vacancy and absorption as first published in C&W’s Q2 2026 Toronto report; Q2 rent as stated in the Q3 report. The Q3 report gives no quarter-over-quarter vacancy change.
Rent Trends: Net Rents Slip 0.8% to C$15.90/SF, a Four-Year Low
The GTA’s average net asking rent slipped to C$15.90/SF/yr in Q3, from C$16.03 in Q2, a four-year low and the tenth straight quarterly decline, according to C&W. The average is 14.5% below the Q1 2024 peak of C$18.60 and 5.6% lower than a year earlier. With additional rent of C$4.45, the average gross cost is C$20.35/SF/yr.
The decline was concentrated in older buildings, where vacancy is highest. GTA Central, with the oldest stock, has the lowest average at C$14.53, 17.7% below its Q4 2022 peak. GTA West fell to C$16.28, 15.5% off its Q3 2023 peak. Markets with more new buildings moved the other way. GTA North rose 0.9% to C$17.49, the highest in the GTA, with Richmond Hill at C$18.13, and GTA East rose to a five-quarter high of C$14.71.
For Tenants
Rents are at a four-year low, and only 15.3% of Q3 deliveries were pre-leased, so tenants have room to negotiate on newer space in GTA North and GTA East, where buildings under five years old hold a large share of the vacancy. Older stock in GTA Central is being priced aggressively. Search Toronto warehouse listings on WareCRE.
Construction Pipeline: 8.3M SF Underway, 2026 Completions Well Below Average
C&W counts 8,264,009 SF under construction. Speculative buildings account for 6.5 million SF and build-to-suit projects 1.8 million SF, all of the latter in GTA West. GTA West holds 5,074,598 SF of the pipeline, followed by GTA Central at 1,826,701 SF, GTA North at 786,380 SF and GTA East at 576,330 SF.
The GTA has completed 3,982,050 SF this year, well short of the 7.1 million SF five-year average for the same period. About 2.5 million SF is due by year-end, 4.6 million SF in 2027, and a 1.2 million SF build-to-suit in Caledon in the first half of 2028. C&W expects 2026 deliveries to land well below the 13.4 million SF annual average of the past three years.
For Operators
Q3 deliveries were only 15.3% pre-leased at completion, down from 42.6% in Q1, and low pre-leasing has meant longer lease-up timelines since 2024. Expect speculative buildings to take time to fill. Limited new supply should cap further upward pressure on vacancy once current projects lease up. Owners of mid-life buildings, 10 to 30 years old, face the least competition, with just 22.0% of vacant space.
Submarket Breakdown
C&W divides the GTA into four submarkets. GTA West carries most of the region’s inventory, demand and new construction.
GTA West (including Mississauga, Brampton and Milton)
GTA West is the largest submarket at 399.6 million SF, with 5.2% vacancy, unchanged on the quarter. It absorbed 584,408 SF in Q3 and 4,130,268 SF year to date, nearly all of the GTA’s total, and leads leasing at 13.7 million SF year to date. An e-commerce tenant leased 246,007 SF at 5525 Countryside Drive in Brampton, and Niche Bakers took 168,476 SF at 165 Summerlea Road. The net asking rent fell to C$16.28/SF/yr. 5,074,598 SF is under construction.
GTA Central (City of Toronto)
GTA Central has 225.6 million SF, and vacancy rose 70 bps on the year to 4.5%, with 79.3% of its vacant space in buildings more than 40 years old. It is the weakest for demand, giving back 579,168 SF in Q3 and 1,433,232 SF year to date as occupiers trade up to newer buildings. The net asking rent is the GTA’s lowest at C$14.53/SF/yr, and 1,826,701 SF is under construction.
GTA North (York Region, including Vaughan)
GTA North has 171.0 million SF at 4.7% vacancy, a 12-year high, with the GTA’s highest net asking rent at C$17.49/SF/yr. It absorbed 465,202 SF in Q3 and 430,374 SF year to date, and led the GTA in completions this year at 1,855,699 SF, including the 510,000 SF building at 11260 Jane Street in Vaughan, which delivered vacant. M-Kite International leased 135,864 SF in Markham.
GTA East (Durham Region)
GTA East is the smallest submarket at 57.6 million SF, with the highest vacancy at 6.1% and a net asking rent of C$14.71/SF/yr, a five-quarter high. It has absorbed 1,036,479 SF this year, and 576,330 SF is under construction. 1702 Tricont Avenue in Whitby (232,201 SF) sold for C$53.4M, or C$229.97/SF.
| Submarket | Inventory | Vacancy | Net Rent (C$/SF/yr) | YTD Net Absorption | Under Construction | Asking Sale Price (C$/SF) |
|---|---|---|---|---|---|---|
| GTA West | 399.6M SF | 5.2% | C$16.28 | 4,130,268 SF | 5,074,598 SF | C$387.16 |
| GTA Central | 225.6M SF | 4.5% | C$14.53 | −1,433,232 SF | 1,826,701 SF | C$368.98 |
| GTA North | 171.0M SF | 4.7% | C$17.49 | 430,374 SF | 786,380 SF | C$492.07 |
| GTA East | 57.6M SF | 6.1% | C$14.71 | 1,036,479 SF | 576,330 SF | C$385.43 |
| GTA total | 853.8M SF | 5.0% | C$15.90 | 4,163,889 SF | 8,264,009 SF | C$409.97 |
Source: Cushman & Wakefield, Toronto (GTA) Industrial MarketBeat Q3 2026.
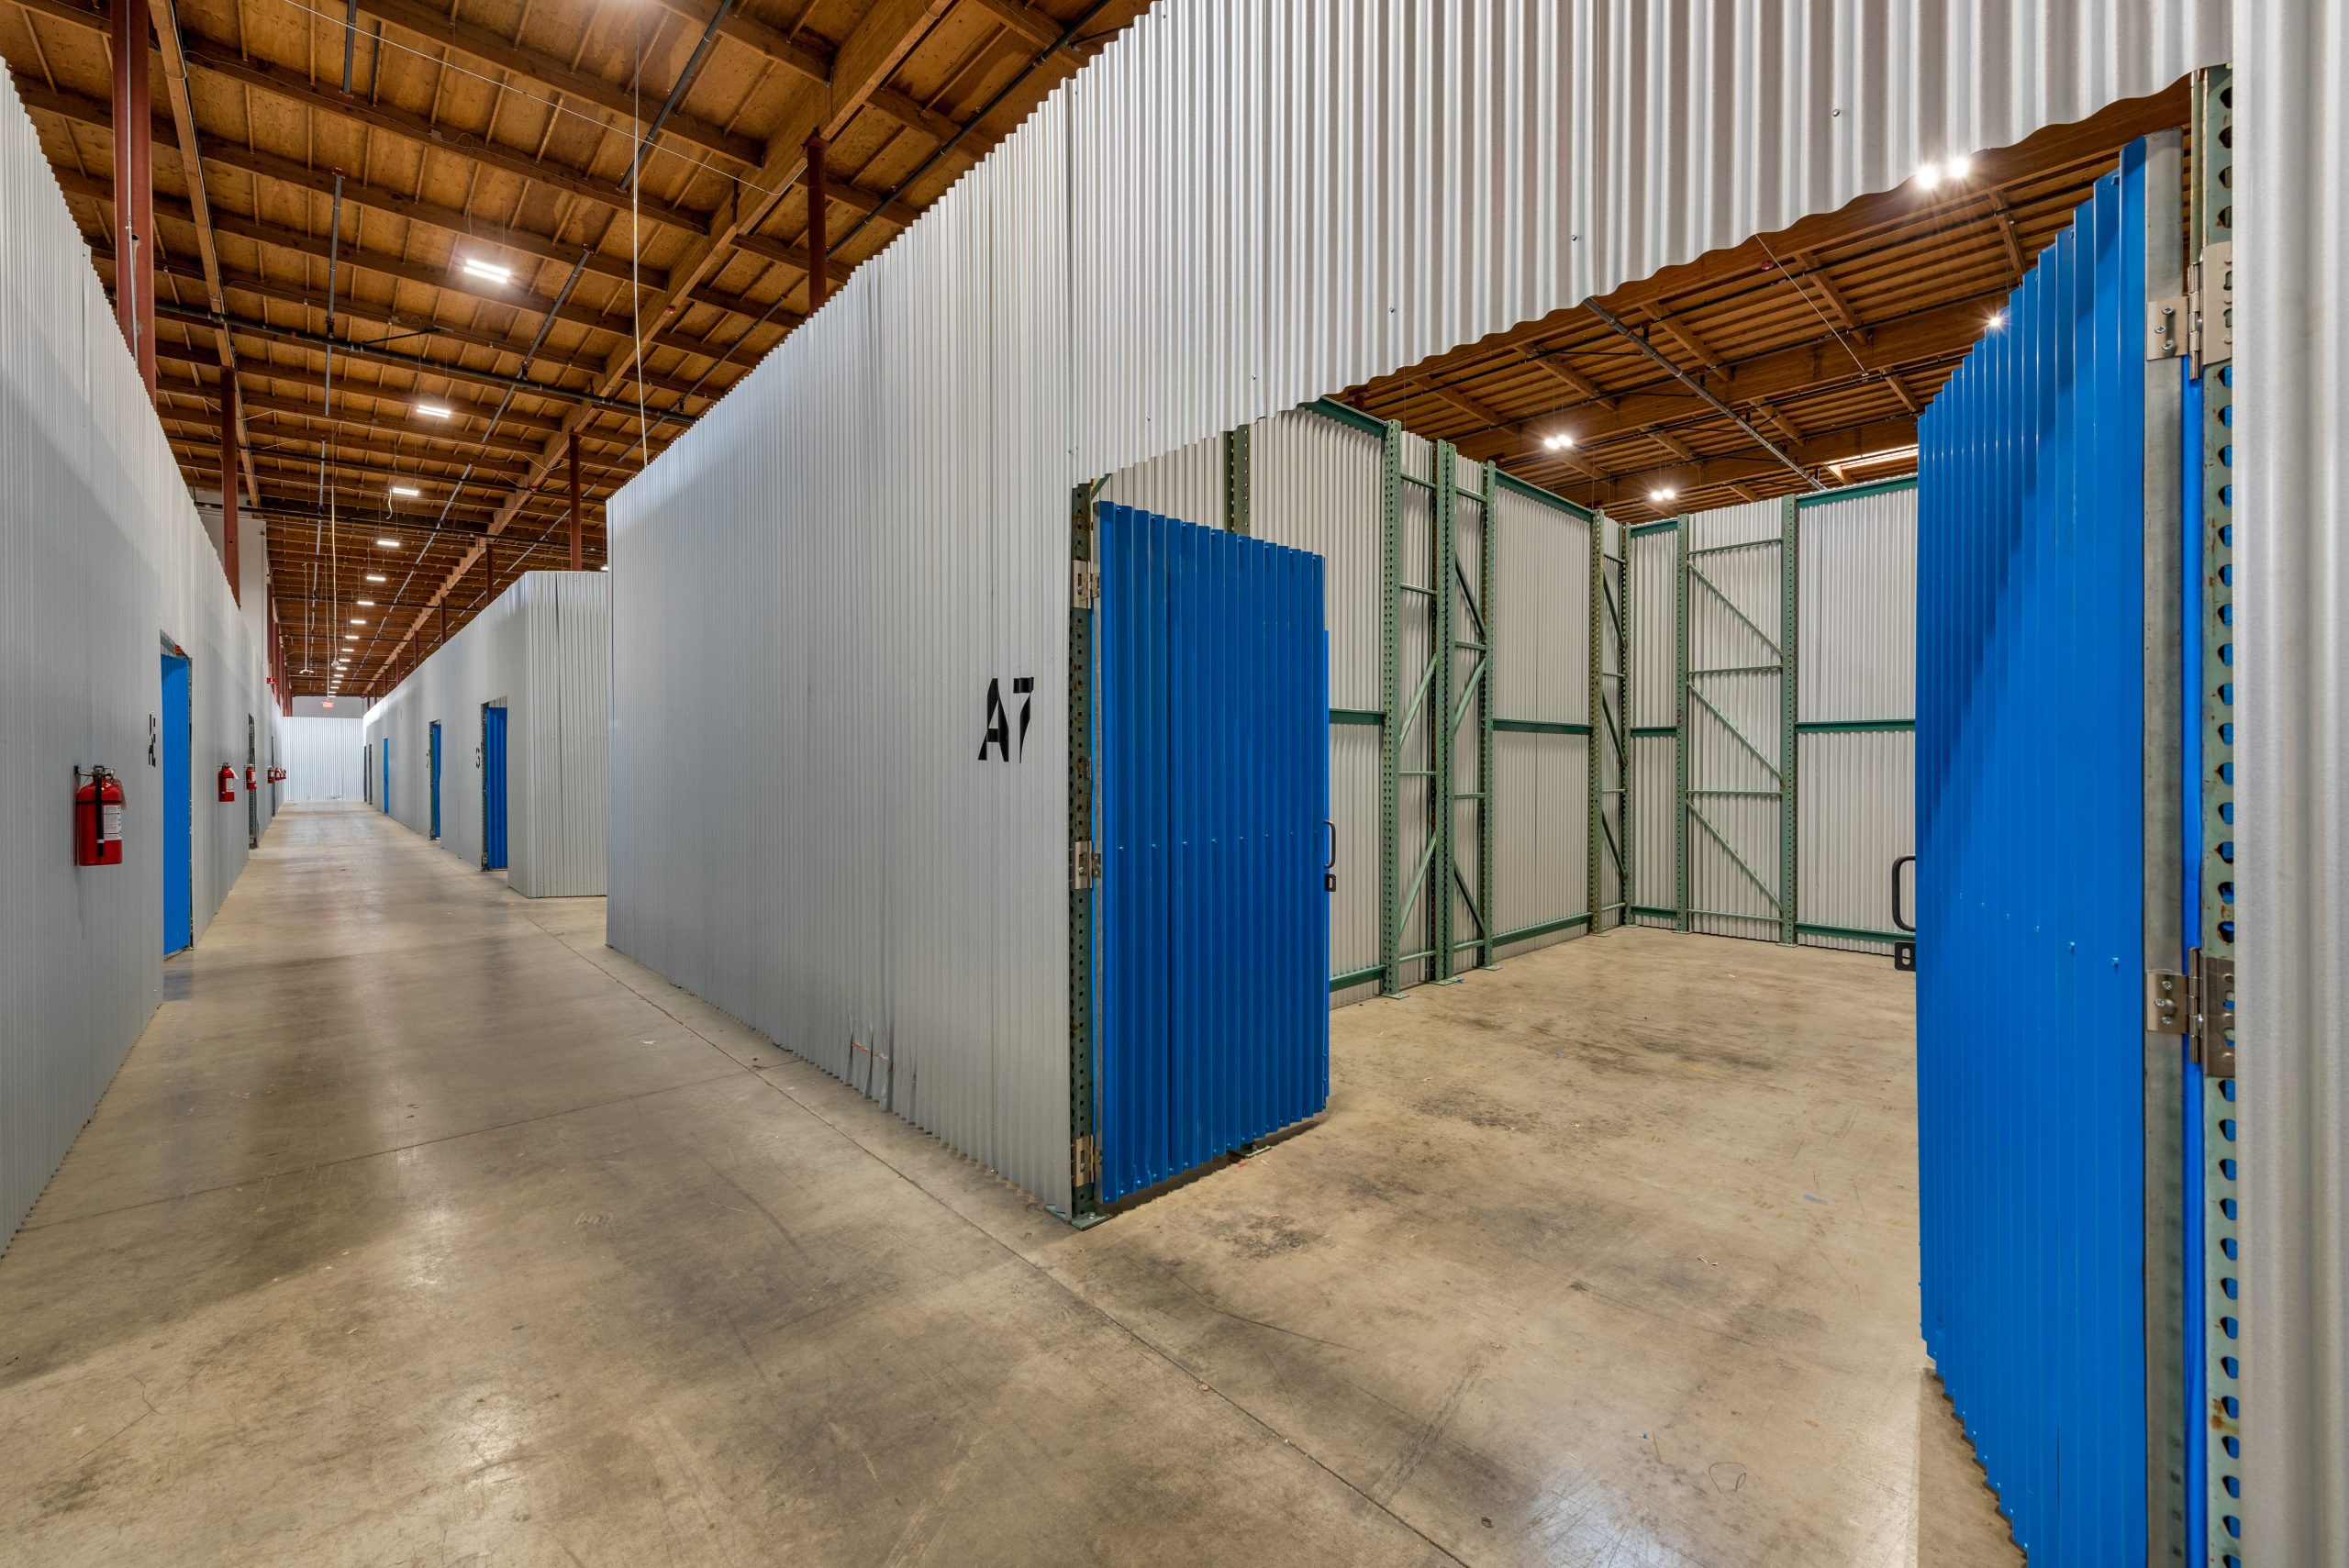
Co-Warehousing & Flexible Warehouse Space in Toronto
Toronto’s co-warehousing market draws on the GTA’s population growth and the steady formation of small businesses that need storage and fulfilment space without a long-term industrial lease.
E-commerce entrepreneurs and DTC brands serving Canada’s largest consumer market account for much of Toronto’s flexible-space demand. Food and beverage businesses, construction and trades firms, importers using Toronto as a Canadian entry point, and event companies round out the tenant mix.
Browse available co-warehousing and small-bay warehouse listings on WareCRE’s Toronto marketplace.
Looking for warehouse space in Toronto?
Key Trends to Watch
1. Absorption Slowed but Stayed Positive
Net absorption slipped to 542,914 SF in Q3 from 2.4 million SF in Q2, the weakest result since mid-2025, but extended just over two years of positive quarters. Year-to-date absorption of 4.2 million SF is only 2.0% behind 2025, and tenants have absorbed 6.4 million SF over the past four quarters. GTA West carried almost all of it; GTA Central is still giving back space.
2. Rents Are Still Adjusting Down, More Slowly
Rents fell 0.8% in Q3, a smaller drop than Q2’s 2.0%, which C&W reads as a slower pace of correction. The average is down 5.6% on the year. The decline is concentrated in older buildings, while GTA North and GTA East, with more new space, ticked up. For the national picture on small and large spaces, see Small-Bay vs. Big-Box: What the Vacancy Gap Means for Tenants and Operators.
3. CUSMA Uncertainty Now Recurs Every Year
At the July 1, 2026 joint review, the United States declined to extend CUSMA (USMCA) for another 16-year term. The agreement remains fully in force, but the three countries must now hold a joint review every year through 2036. C&W calls trade policy uncertainty a potential headwind, particularly for occupiers tied to cross-border supply chains, and private-sector forecasters have cut Ontario’s 2026 real GDP growth outlook to 0.6% from 1.1%. For more on trade and warehouse demand, see How Tariffs Are Reshaping Warehouse Demand in 2026.
Outlook: What to Watch in Early 2027
C&W’s year-end 2026 MarketBeats are expected in mid-January. Three indicators will set the direction into 2027.
Watch whether rents stabilize. The Q3 decline of 0.8% was smaller than Q2’s. A flat Q4 reading near C$15.90/SF/yr would point to a bottom.
Watch sublease availability. C&W says sublease trends will give the clearest signal of any softening in occupier demand, after absorption slowed to 542,914 SF in Q3.
Watch whether new buildings lease. About 2.5 million SF is due by year-end. Pre-leasing on those deliveries, after Q3’s 15.3%, will show how much pressure new supply puts on vacancy into 2027.
Find warehouse space in Toronto
Browse co-warehousing, small-bay, and distribution listings across the Greater Toronto Area.
Data sources: Cushman & Wakefield Toronto (GTA) Industrial MarketBeat Q3 2026 (headline and submarket figures; rents net asking, C$/SF/yr); Cushman & Wakefield Canada Industrial MarketBeat Q3 2026 (additional and gross rent); White & Case, July 2, 2026 (CUSMA/USMCA joint review). Each report reflects the most recent vacancy, rental, and construction data available at the time of publication. We refresh our reports as new market data is released, and we’re continually expanding coverage to additional metros.
Related Resources
Frequently Asked Questions
What is the current industrial vacancy rate in Toronto?
GTA industrial vacancy was 5.0% in Q3 2026, according to Cushman & Wakefield, up 10 basis points from 4.9% a year earlier, a change C&W calls effectively flat. Q2’s published rate was also 4.9%. By submarket, GTA Central was tightest at 4.5% and GTA East highest at 6.1%.
How much does warehouse space cost in Toronto?
The GTA average net asking rent was C$15.90/SF/yr in Q3 2026, down 0.8% on the quarter and 5.6% on the year. Additional rent averaged C$4.45, for a gross cost of about C$20.35/SF/yr. Net rents ranged from C$14.53 in GTA Central to C$17.49 in GTA North.
Which GTA submarket is best for warehouse space?
It depends on the requirement. GTA West is the largest and most active market, with 4,130,268 SF absorbed this year and the most new construction. GTA Central has the lowest rent at C$14.53/SF/yr and the tightest vacancy at 4.5%, but much of its stock is older. GTA North has the highest rent at C$17.49/SF/yr and many newer buildings with vacancy.
How much industrial space is under construction in Toronto?
8,264,009 SF was under construction at the end of Q3 2026, 78.7% of it speculative. About 2.5 million SF is due by year-end, and C&W expects 2026 deliveries to land well below the 13.4 million SF annual average of the past three years.