Charlotte Industrial & Warehouse Market Report | Q3 2026
Key Takeaways
- Charlotte industrial vacancy rose to 7.8% in Q3 2026, per Cushman & Wakefield, the first increase in six quarters, as 1.9 million SF of mostly vacant speculative space delivered. It is still 50 basis points below a year earlier.
- Overall asking rents eased 0.6% to $8.60/SF/yr NNN, which C&W calls the first quarterly decline in 23 quarters, and still close to the $8.66 high set in Q1 2026. Flex space averaged $14.22/SF/yr.
- Net absorption was 651,631 SF in Q3 and 4.7 million SF year to date, the 22nd straight quarter of occupancy gains. Year-to-date leasing of 9.7 million SF already exceeds the full-year 2024 total.
- 7.9 million SF is under construction, up 4.9% on the quarter as nine projects broke ground, and 65.4% of it is speculative.
Browse warehouse space for rent in Charlotte
7.8%
Overall Vacancy (Q3 2026)
$8.60
Avg. Asking Rent ($/SF/yr NNN)
652K
SF Net Absorption (Q3 2026)
7.9M
SF Under Construction
Charlotte’s vacancy turned up in Q3 2026 for the first time in six quarters. Occupiers still absorbed 651,631 SF, the 22nd straight quarterly gain, but 91.4% of the 1.9 million SF delivered in the quarter arrived vacant, and vacancy rose 30 basis points to 7.8%. Rents eased for what C&W calls the first time in 23 quarters as larger below-market blocks came available. C&W expects vacancy to stay flat in the near term as move-ins offset new supply.
Figures are from Cushman & Wakefield’s Q3 2026 Charlotte Industrial MarketBeat unless noted. Prior-quarter and year-ago comparisons use the figures as restated in C&W’s Q3 2026 U.S. Industrial MarketBeat tables. Rents are net asking, quoted in $/SF/yr. Other brokers measure Charlotte differently, and we do not combine their series.
Market Snapshot: Q3 2026
| Metric | Q3 2026 | Q2 2026 (restated) | YoY or note |
|---|---|---|---|
| Overall vacancy | 7.8% | 7.5% | ↓50 bps YoY (8.3% in Q3 2025) |
| Overall asking rent ($/SF/yr NNN) | $8.60 | $8.65 | +2.0% YoY (from $8.43); first QoQ decline in 23 quarters per C&W’s Charlotte report |
| Flex asking rent ($/SF/yr) | $14.22 | n/a | Highest-priced product type |
| Net absorption | 651,631 SF | 1.1M SF | 4.7M SF year to date; 22nd straight positive quarter |
| New leasing activity | 2.5M SF | n/a | 9.7M SF year to date |
| Deliveries | 1.9M SF | n/a | 4.0M SF year to date; 91.4% of Q3 space vacant on delivery |
| Under construction | 7.9M SF | n/a | +4.9% QoQ; 65.4% speculative |
| Inventory | 320.6M SF | n/a | 15 submarkets |
Source: Cushman & Wakefield, Charlotte Industrial MarketBeat Q3 2026. Q2 2026 and Q3 2025 values as restated in C&W’s U.S. Industrial MarketBeat Q3 2026 metro tables. n/a = not restated in the Q3 reports.
Rent Trends: First Dip in 23 Quarters, Still Near the High
Overall asking rents eased 0.6% to $8.60/SF/yr NNN in Q3 2026, which C&W’s Charlotte report calls the first quarterly decrease in 23 quarters. Rents rose 72.0% over that stretch and remain close to the $8.66 high set in Q1 2026. C&W attributes the dip to larger blocks of below-market space coming available, while steady demand for premium product kept removing higher-priced options. Flex space averaged $14.22/SF/yr.
Charlotte asks less than the national average. The U.S. overall rent in C&W’s Q3 release is $10.40/SF/yr NNN. Among the submarkets in the table below, warehouse rents run from $7.62/SF/yr in Rowan and Lincoln Counties to $10.26/SF/yr at the Airport. C&W expects rents to resume rising as demand for high-quality space persists.
For Tenants
Tenants have a little more room this quarter. Larger below-market blocks came available, and most of Q3’s new speculative space delivered vacant. Big-box options are scarce, though. C&W counts only two existing or under-construction availabilities of 500,000 SF or more. The widest choice is in the North submarket (11.6% vacant), Rowan County (17.0%) and Lincoln County (16.2%). Search Charlotte warehouse listings on WareCRE.
Construction Pipeline: 7.9M SF Underway as Nine Projects Break Ground
Charlotte had 7.9 million SF under construction at the end of Q3 2026, up 4.9% on the quarter as nine projects broke ground. Speculative projects make up 5.2 million SF, or 65.4%. Fifteen buildings delivered 1.9 million SF in Q3, 91.4% of it vacant on completion, bringing year-to-date completions to 4.0 million SF.
Cabarrus County has the largest pipeline at 2.7 million SF, followed by the Southwest (1.3 million SF) and York County (1.2 million SF) submarkets. In York County, construction began on FireTower 77, a 1.0 million SF speculative project and the only building of that size under construction in the Carolinas. Preleasing improved, highlighted by FedEx leasing and occupying 13021 General Dr in the Southwest submarket.
For Operators
Speculative supply is the near-term risk. Most of Q3’s deliveries arrived vacant, and 5.2 million SF more speculative space is underway. Demand is steady, with 22 straight quarters of occupancy gains, and C&W expects anticipated move-ins to keep vacancy within a healthy range. Owners of modern big-box space face little competition, since only two availabilities of 500,000 SF or more exist or are underway.
Submarket Breakdown: York County Led Q3 Absorption, Cabarrus Leads Construction
C&W tracks 15 Charlotte submarkets across the core city and surrounding counties in North and South Carolina. The four below are the largest or most active by Q3 2026 leasing, absorption and construction.
Southwest
The largest submarket at 51.3 million SF, 7.5% vacant, and the source of 22.8% of the metro’s new leasing this year. In Q3, West Logistics renewed and expanded to 438,650 SF at 11701 Goodrich Dr, adding 221,750 SF, and FedEx leased and occupied 13021 General Dr. Absorption was negative 106,983 SF in Q3 but 310,031 SF positive year to date, and 1.3 million SF is under construction. Warehouse space asks $8.90/SF/yr.
Airport
Charlotte’s main logistics submarket, anchored by Charlotte Douglas International Airport and I-77/I-85 access. Vacancy is 7.6%. It absorbed 283,722 SF in Q3 and 1.4 million SF year to date, the most of any submarket. Foundry Commercial’s four-building Runway Logistics project added 394,211 SF this year, and 820,118 SF is under construction. Its warehouse rent of $10.26/SF/yr is the highest among Charlotte’s core submarkets.
Cabarrus County
Northeast of the city along I-85, with 24.6 million SF and 7.4% vacancy. The county has the metro’s largest pipeline at 2.7 million SF, and Concord Commerce Center and 85 Exchange delivered 392,040 SF and 301,900 SF this year. Absorption was roughly flat in Q3 at negative 5,990 SF and is 614,273 SF positive year to date. Warehouse space asks $8.33/SF/yr.
York County (SC)
On the South Carolina side along I-77, with 32.6 million SF and 7.3% vacancy. It led the metro in Q3 absorption at 550,244 SF. Legrand North America renewed 344,050 SF at Carowinds Distribution Center, and Foundry’s CenterPoint Carolinas delivered 464,384 SF this year. Construction began on FireTower 77, a 1.0 million SF speculative building, and Octapharma announced a $1.5 billion manufacturing project in the county. Warehouse space asks $8.74/SF/yr.
| Submarket | Vacancy | W/D Asking Rent ($/SF/yr) | YTD Net Absorption (SF) | Under Construction (SF) |
|---|---|---|---|---|
| Southwest | 7.5% | $8.90 | 310,031 | 1,310,227 |
| North | 11.6% | $8.95 | 632,255 | 914,397 |
| Airport | 7.6% | $10.26 | 1,351,544 | 820,118 |
| York County | 7.3% | $8.74 | 680,465 | 1,198,765 |
| Gaston County | 10.9% | $7.83 | 747,873 | 462,000 |
| Iredell County | 4.7% | $7.75 | 150,549 | 0 |
| Cabarrus County | 7.4% | $8.33 | 614,273 | 2,737,250 |
| Rowan County | 17.0% | $7.62 | 379,908 | 0 |
| Lincoln County | 16.2% | $7.62 | 0 | 0 |
| Charlotte total | 7.8% | $8.56 | 4,740,388 | 7,936,661 |
Source: Cushman & Wakefield, Charlotte Industrial MarketBeat Q3 2026, market statistics table (selected submarkets; totals include all 15). Vacancy is overall vacancy; rents are weighted net asking, $/SF/yr.
Co-Warehousing & Flexible Warehouse Space in Charlotte
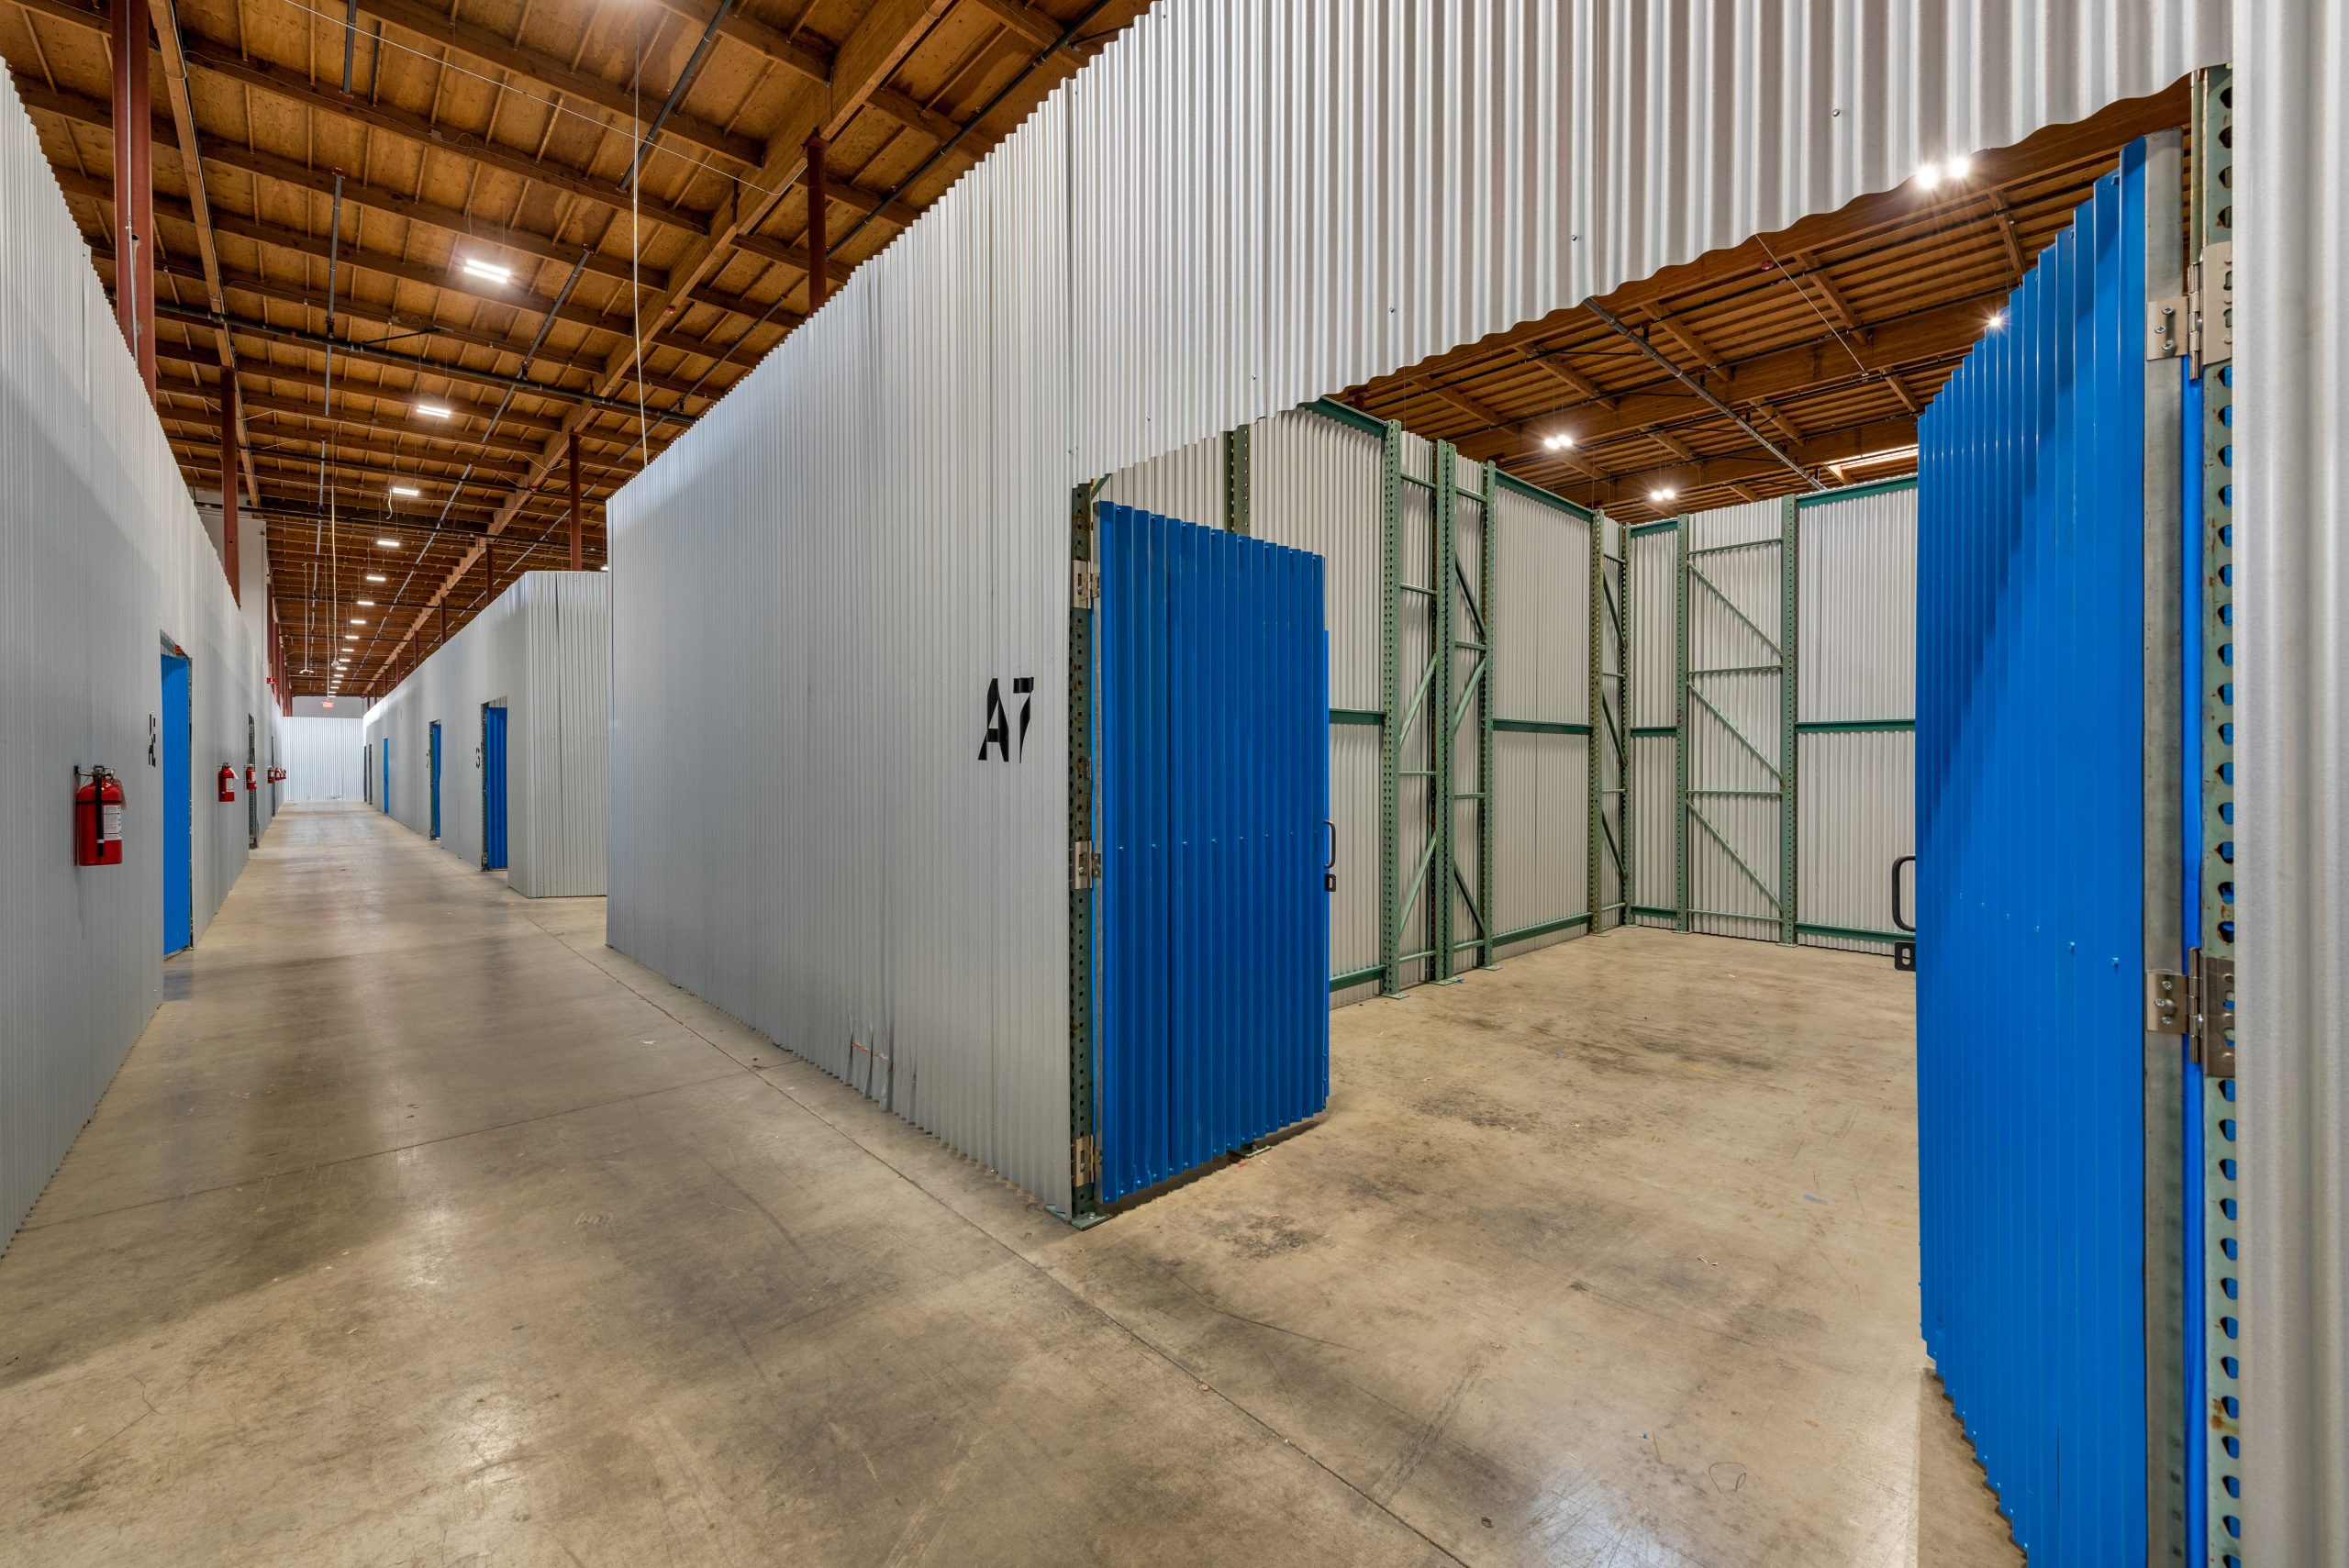
Charlotte’s large small-business economy creates steady demand for operating space in smaller increments and on shorter terms. Flex space is the highest-priced product type in the metro at $14.22/SF/yr.
Small-bay space softened earlier this year. For buildings under 125,000 SF, Matthews, citing CoStar data, reported 5.5% vacancy, asking rents of $12.22/SF (up 3.4% year over year) and negative absorption of 295,000 SF in Q2 2026.
Charlotte’s flex demand starts with e-commerce businesses using the metro’s I-85/I-77 access and building trades serving its residential growth. Financial services firms needing records and fulfillment space, Carolinas food and beverage distributors and manufacturing startups add to it.
Browse available co-warehousing and small-bay warehouse listings on WareCRE’s Charlotte marketplace.
Looking for warehouse space in Charlotte?
Key Trends to Watch
1. Vacancy Rose for the First Time in Six Quarters
Charlotte’s vacancy fell for five straight quarters before rising 30 bps to 7.8% in Q3 2026. New supply drove the increase. Occupancy grew by 651,631 SF, but 91.4% of the 1.9 million SF delivered was vacant on completion. Vacancy rose in both the urban core, to 8.4%, and the outlying counties, to 7.4%.
2. Leasing Has Already Passed All of 2024
New leasing totaled nearly 2.5 million SF in Q3 and 9.7 million SF year to date, more than the full-year 2024 total. Urban core submarkets captured 69.1% of Q3 leasing, and the Southwest submarket accounts for 22.8% of the year’s total. Charlotte’s economy supports the demand. The metro added 20,600 jobs over the past year, up 1.5%, fifth among the markets C&W tracks.
3. Big-Box Options Are Down to Two
C&W counts only two existing or under-construction big-box availabilities of 500,000 SF or more. One is FireTower 77, the 1.0 million SF speculative building that broke ground in York County in Q3. Small-bay space moved differently earlier this year. Matthews, citing CoStar data, reported negative small-bay absorption in Q2 even as small-bay vacancy stayed low at 5.5%. Owners and tenants should price the two segments separately. Full analysis: Small-Bay vs. Big-Box: What the Vacancy Gap Means in 2026. For broader context: Industrial Real Estate Trends & Outlook 2026.
Outlook: What to Watch in Early 2027
C&W’s year-end 2026 MarketBeats are expected in mid-January. They will show whether demand keeps pace with the speculative supply now delivering.
Vacancy trend. C&W expects vacancy to stay flat in the near term, with tenant move-ins offsetting vacant new supply. Watch whether the rate holds near 7.8% as more speculative space delivers.
Rent direction. Rents dipped 0.6% in Q3, but C&W expects them to resume rising as demand for high-quality space persists. A Q4 increase would confirm the dip was a mix effect.
Investment sales. Q3 sales topped $556.0M across 15 deals, led by CBRE Investment Management’s $134.7M purchase of North Charlotte Commerce Center. C&W expects rising interest rates and stricter underwriting to slow sales, though strong leasing and creditworthy tenants may sustain volume.
Find warehouse space in Charlotte
Browse co-warehousing, small-bay, and distribution listings across the Charlotte metro.
Data sources: Cushman & Wakefield Charlotte Industrial MarketBeat Q3 2026 (headline, submarket, product-type and investment-sale figures; rents net asking, $/SF/yr); Cushman & Wakefield U.S. Industrial MarketBeat Q3 2026 (restated Q2 2026 and Q3 2025 figures and U.S. averages; rents NNN); Matthews Charlotte, NC Industrial Market Report Q2 2026, citing CoStar data (small-bay figures, cap rates and sale pricing only). Each report reflects the most recent vacancy, rental, and construction data available at the time of publication. We refresh our reports as new market data is released, and we’re continually expanding coverage to additional metros.
Related Resources
Frequently Asked Questions
What is the current industrial vacancy rate in Charlotte?
Charlotte industrial vacancy was 7.8% in Q3 2026, according to Cushman & Wakefield, up 30 basis points from Q2 and down 50 basis points from a year earlier. It was the first increase in six quarters, driven by vacant speculative deliveries. Submarket rates range from 0.5% in Cleveland County to 17.0% in Rowan County.
How much does warehouse space cost in Charlotte?
The overall average asking rent was $8.60/SF/yr NNN in Q3 2026, down 0.6% on the quarter and up 2.0% year over year. Flex space averaged $14.22/SF/yr. Across the submarkets profiled on this page, warehouse rents run from $7.62/SF/yr in Rowan and Lincoln Counties to $10.26/SF/yr at the Airport. For buildings under 125,000 SF, Matthews reported asking rents of $12.22/SF in Q2 2026, citing CoStar data.
Which Charlotte submarket is best for warehouse space?
It depends on the requirement. The Airport submarket has the highest warehouse rents among the core submarkets and leads the metro in year-to-date absorption. Southwest is the largest submarket at 51.3 million SF and leads in new leasing. Cabarrus County, along I-85, has the largest pipeline at 2.7 million SF. York County (SC) offers I-77 access on the South Carolina side and led Q3 absorption, and Rowan and Lincoln Counties have the highest vacancy rates.
How much industrial space is under construction in Charlotte?
7.9 million SF was under construction at the end of Q3 2026, up 4.9% from Q2 after nine projects broke ground, and 65.4% of it is speculative. Q3 deliveries totaled 1.9 million SF, 91.4% vacant on completion, and year-to-date completions reached 4.0 million SF. Cabarrus County has the largest pipeline at 2.7 million SF.
What are industrial cap rates in Charlotte?
Matthews, citing CoStar data, reported an average industrial cap rate of 7.2% in Q2 2026 and an average sale price of $119 per SF. For buildings under 125,000 SF, it reported a 5.7% cap rate and $165 per SF. Cushman & Wakefield’s MarketBeat does not publish a Charlotte cap rate. The largest Q3 sale it recorded was CBRE Investment Management’s $134.7M purchase of North Charlotte Commerce Center in Iredell County, more than 929,000 SF across three buildings.